Written by: Roshan R
Research by: Abra
Walk into any conversation about personal finance in India today and there is a good chance the topic will come up sooner or later. Not stocks. Not crypto. Not even fixed deposits. It is the simple habit of putting a fixed amount into mutual funds every month.
That change is bigger than it looks.
That is one reason SIP investing has become such a powerful habit in India in 2026.
The numbers are difficult to ignore. SIP contributions have stayed above ₹30,000 crore in recent months, with some months moving beyond ₹31,000 crore. Total assets linked to these SIPs have also crossed ₹17 lakh crore. Those figures tell us that this is no longer a small corner of the investment industry. It has become a major source of domestic savings.
But the most interesting part is not the size. It is the behaviour behind it.
People keep investing when markets are rising, and, more importantly, many continue when markets are falling. The amount leaves the bank account automatically, month after month. There is no need to decide whether today is the right day to buy. That removes one of the biggest problems investors face: their own emotions.
From Fixed Deposits to Automatic Investing
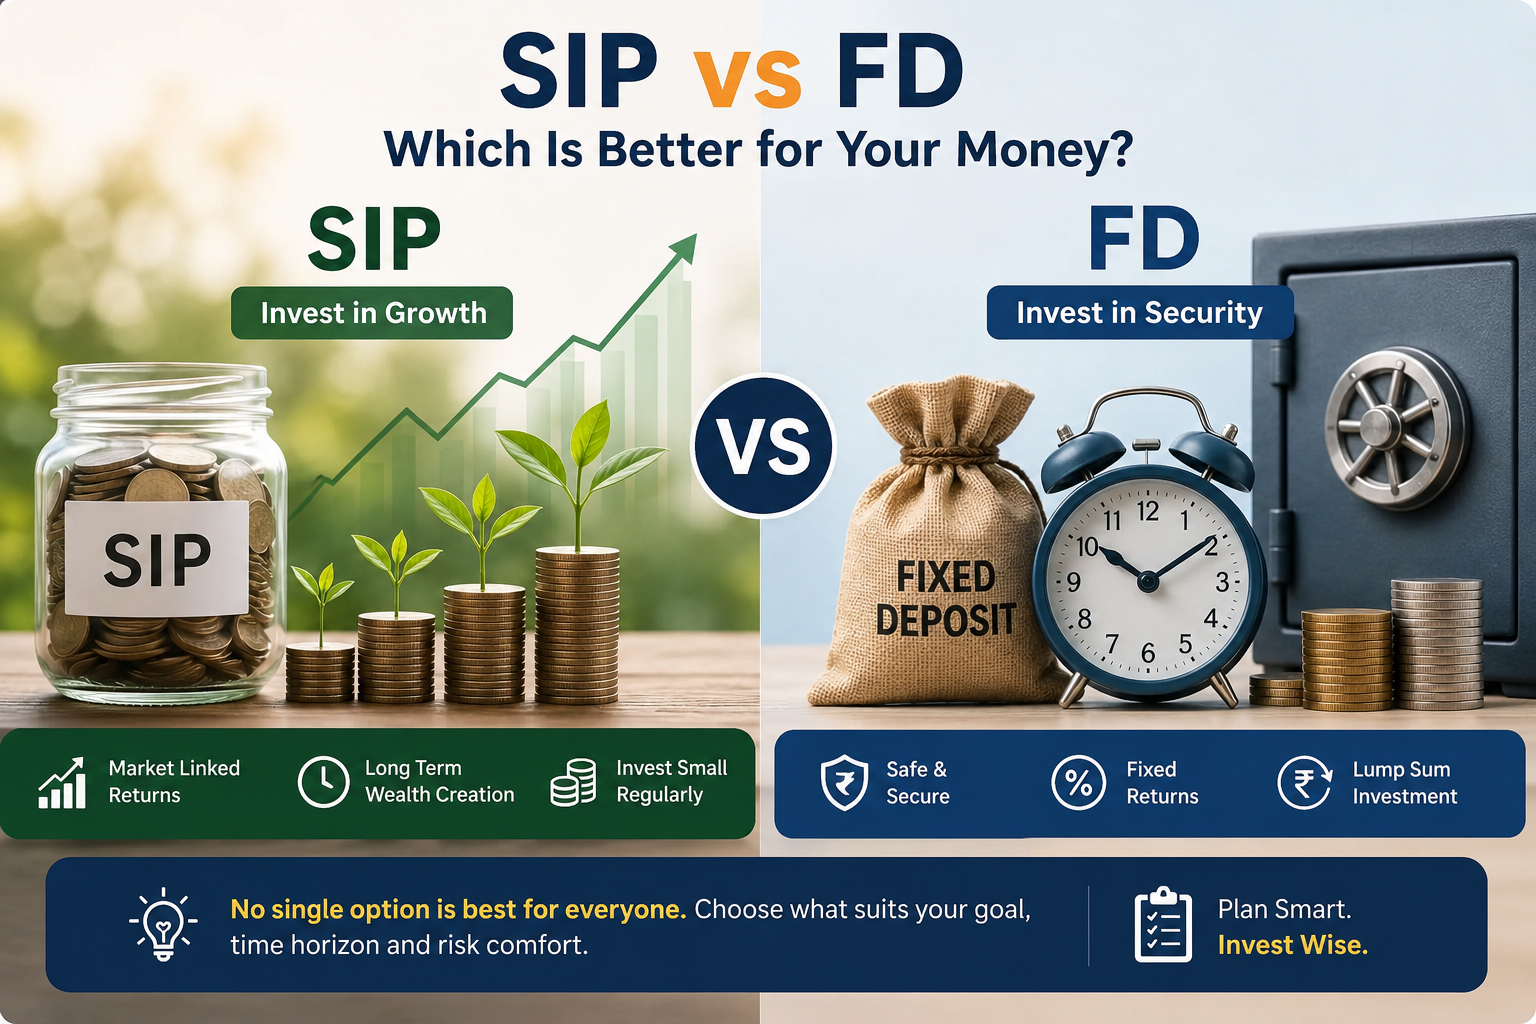
For a long time, fixed deposits were the comfortable choice for Indian families. They were familiar, easy to understand and felt safe. Gold and property also had a strong place in household thinking.
Mutual funds were different. Many people associated them with the stock market, and the stock market was associated with risk. That created a psychological barrier.
Technology has slowly broken that barrier.
UPI and automatic bank payments have made recurring investments almost invisible. Investment apps have made the process easier to understand. A person does not need to visit an office or fill out piles of paperwork every month. Once the instruction is set up, the investment can happen automatically.
Then there is social media. YouTube creators, finance pages, Instagram reels and online communities have put investing vocabulary in front of millions of people who may never have opened a financial newspaper. Words such as mutual funds, compounding and index funds are now part of everyday conversations.
The result is a change in mindset. Investing is increasingly being treated like a monthly expense rather than a special event.
And this is not limited to Mumbai, Delhi, Bengaluru or Hyderabad. Smaller cities and towns are becoming an important part of the story. Young workers are starting early, sometimes with their first regular salary. For them, investing is less about becoming a market expert and more about building a routine.
Why Consistency Matters More Than Excitement
The market loves excitement. Every week there is a new stock, sector or fund getting attention. One month small-cap funds are popular. The next month investors are talking about flexi-cap funds, gold or international opportunities.
That noise can distract from the real advantage of a SIP plan: consistency.
When markets fall, the same amount of money can buy more units. When prices rise, it buys fewer. Over a long period, the investor keeps participating without having to predict every market move.
That does not mean losses disappear. Markets can fall sharply, and mutual funds can lose value. The point is that a disciplined investor does not have to make a perfect decision every month.
This is particularly important because timing the market is much harder than it looks. Investors often feel confident after prices have already risen and become nervous after prices have fallen. By then, emotions are influencing the decision.
A SIP can create a useful barrier between the investor and that emotional cycle.
The Bigger Story: Domestic Money
There is another reason this trend matters in 2026. India's market is no longer dependent only on foreign investors for its direction.
When foreign institutional investors sell heavily, Indian markets can face significant pressure. But domestic institutions and retail investors have become a stronger counterweight. SIP mutual fund contributions are one part of that domestic pool.
During periods of volatility, this steady flow can help absorb some selling pressure. It does not guarantee that markets will stay up, and it certainly cannot prevent every correction. But a large and growing base of domestic investors can make the market less dependent on money coming from outside the country.
That is a structural change, not just a good headline.
It also changes the relationship between ordinary households and the stock market. A person may never directly buy a single share, yet their monthly investment can still make them a participant in India's economic growth.
Compounding Is the Quiet Attraction
Ask an experienced investor what they value most about a long-term SIP and the answer may not be high returns. It may be time.
Compounding works slowly at first. The early years can feel underwhelming because the investment amount is still small. But as contributions continue and returns remain invested, the growth can become more noticeable.
For example, someone investing ₹5,000 a month may not feel that the first few years are changing their financial life. Over a decade or more, however, the combination of regular contributions and potential investment growth can become substantial.
Of course, actual returns are never guaranteed. The final value depends on market performance, costs, the chosen fund and the length of time invested.
Still, the basic lesson is powerful: starting early can matter more than trying to find the perfect investment.
The Danger of Chasing the Winner
There is one trap that becomes easier to fall into when investing becomes popular: chasing whatever performed best recently.
If a small-cap fund has delivered impressive returns, investors may rush toward small caps. If gold suddenly performs well, everyone starts discussing gold. If a particular sector is booming, social media can make it feel as though missing it means missing the entire market.
That approach can be risky.
Past performance does not tell you what will happen next. A fund that has recently delivered strong returns can experience a sharp correction. A category that looks boring today can perform well later.
The better question is not, “What is winning this month?” It is, “Does this investment match my goal, time horizon and ability to handle losses?”
That sounds less exciting, but personal finance is usually about making sensible decisions rather than exciting ones.
A Habit That May Last
The biggest change in India's investment culture may not be a particular fund or app. It may simply be the idea that investing should happen regularly.
The traditional FD-and-gold mindset is not disappearing overnight. Indians will continue to value safety, physical assets and guaranteed returns. But a new generation is adding another layer to that financial picture.
They are saving automatically. They are learning about markets through their phones. They are starting earlier. And they are becoming more comfortable with the idea that wealth can be built gradually instead of through one big financial decision.
That is why the growth of SIPs in 2026 deserves attention.
For someone starting with ₹500 or ₹5,000 a month, the amount may look small. It may not feel important at the beginning. But habits rarely look powerful on day one.
The real test is what happens after ten years of staying invested, increasing contributions when income grows, and refusing to panic every time the market becomes uncomfortable.
There is no magic button here. Mutual funds carry market risk, and a SIP cannot guarantee profits. Investors should understand the scheme they choose, read the relevant documents, consider their financial goals and seek professional advice when necessary.
Still, something meaningful is happening.
India is gradually moving from a culture where investing was often postponed until people felt they had “enough money” to one where investing can begin with whatever amount fits the household budget.
SIP works because SIP removes daily decisions.
And perhaps that is the real story of 2026. The obsession is not really about mutual funds. It is about habit. Millions of people are discovering that building wealth does not always require a dramatic move. Sometimes it simply means making a reasonable decision, automating it, and giving it enough time to work for millions of Indians.